
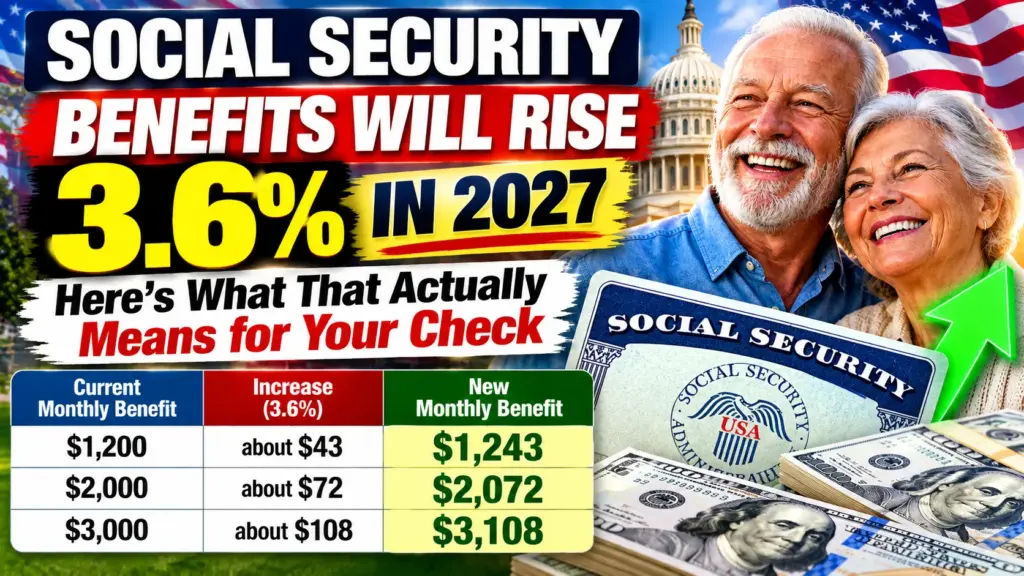
The Social Security Administration announced the 2027 Social Security COLA on Wednesday: a 3.6% cost-of-living increase for about 76 million Americans who receive Social Security or Supplemental Security Income. It’s the largest annual bump since the 8.7% adjustment in 2023, and it follows a 2.8% increase this year.
A bigger percentage sounds like good news, and in a narrow sense it is. But a COLA is only worth what it buys, and between higher prices and Medicare premiums, the number on the announcement and the number that actually lands in your account can feel quite different.
AI Could Cut Demand for 36 Million US Jobs by 2035.
How Much Will Your Social Security Check Go Up in 2027?
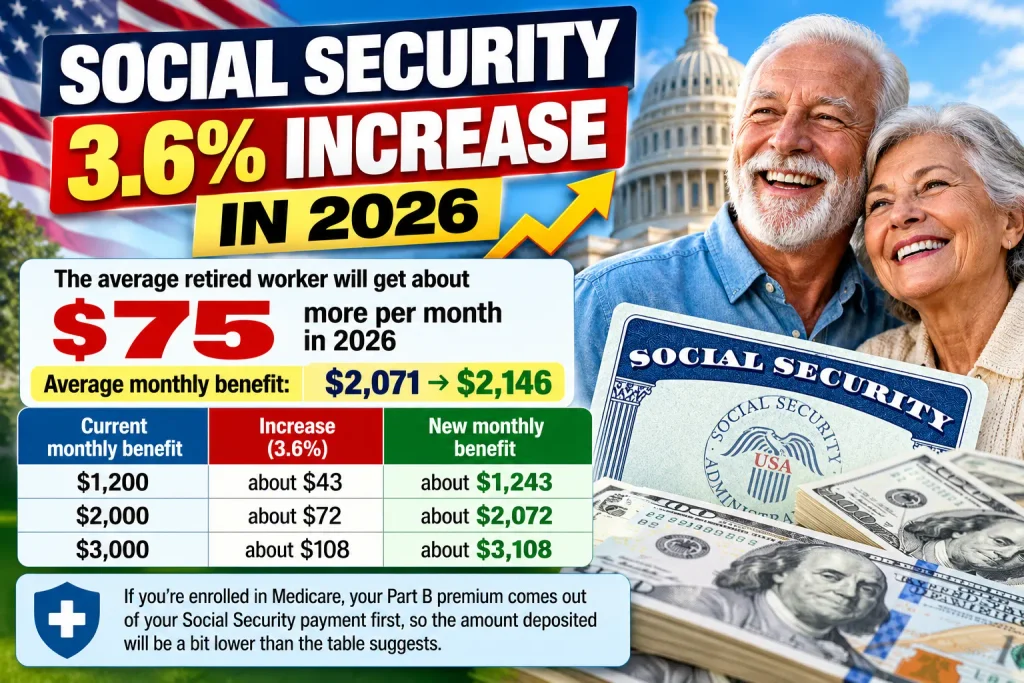
The math is simple: your current benefit multiplied by 3.6%. The Social Security Administration reported that the average retired worker received about $2,071 a month at the start of 2026. A 3.6% increase adds roughly $75 a month, bringing that average to around $2,146.
Here’s what the same increase looks like at different benefit levels:
| Current monthly benefit | Increase (3.6%) | New monthly benefit |
|---|---|---|
| $1,200 | about $43 | about $1,243 |
| $2,000 | about $72 | about $2,072 |
| $3,000 | about $108 | about $3,108 |
Those are before-deduction figures. If you’re enrolled in Medicare, your Part B premium comes out of your Social Security payment first, so the amount deposited will be a bit lower than the table suggests. The exact new amount will be confirmed in your COLA notice.
When Does the 2027 COLA Start?
There are two start dates, depending on which benefit you get.
- Supplemental Security Income (SSI): about 7.3 million recipients will see the higher payment starting December 31, 2026.
- Social Security retirement, disability, and survivor benefits: nearly 72 million beneficiaries will see the increase in their January 2027 payments.
The Social Security Administration says most people will be able to read their COLA notice online in late November through the Message Center of their my Social Security account, as long as the account was created by November 18. Paper notices go out by mail in December.
How the COLA Is Actually Calculated
The adjustment isn’t set by Congress or the White House each year. By law, it’s tied to inflation as measured by the Consumer Price Index for Urban Wage Earners and Clerical Workers, usually shortened to CPI-W. The agency compares the average CPI-W for July, August, and September this year with the same three months last year. The percentage increase becomes the COLA. If prices don’t rise, there’s no increase.
That’s why the announcement always comes on the same day as the September inflation report: that report completes the three-month average. Forecasters had converged on a range of roughly 3.4% to 3.6% beforehand, and the final number landed at the top of it.
SpaceX Just Rattled Verizon, AT&T and T-Mobile in a Single Day.
Why Many Retirees Won’t Feel the Full Raise
Here’s the honest part. A 3.6% COLA is meant to keep benefits from losing purchasing power, not to make anyone better off. With consumer prices up around 3.4% to 3.5% from a year ago as of August, the raise roughly tracks inflation rather than beating it.
There are two reasons it can feel smaller than it sounds.
First, Medicare premiums. Part B premiums are deducted directly from Social Security payments, so any increase in the premium eats into the COLA before you ever see it. The 2027 Medicare numbers hadn’t been published at the time of this announcement, so it’s worth checking once they’re out.
Second, the index itself. CPI-W tracks the spending habits of working-age wage earners, while retirees tend to spend a bigger share of their income on housing and health care, categories that can move at a different pace than the overall index. The Senior Citizens League, an advocacy group, has pointed out that a retiree’s personal inflation rate can therefore run higher or lower than the number the COLA is based on, and it expects many seniors to end up disappointed in the long run.
Energy costs are part of the backdrop too. With gas prices above $4 a gallon on a record number of days this year and diesel near record levels, everyday costs for people on fixed incomes have been under real pressure, which is exactly the situation a COLA is designed to address.
Other Social Security Numbers That Change in 2027
The COLA gets the headlines, but a few other figures update at the same time:
- Taxable maximum: The maximum amount of earnings subject to Social Security tax rises to $192,300.
- Earnings limit if you’re under full retirement age all year: $25,560, up from $24,480 in 2026. Benefits are reduced by $1 for every $2 you earn above that.
- Earnings limit in the year you reach full retirement age: $67,920, up from $65,160. Benefits are reduced by $1 for every $3 above it, until the month you reach full retirement age.
- At or past full retirement age: there’s no earnings limit at all.
If you’re collecting benefits while still working, the earnings limit is the number most likely to cost you money if you ignore it.
What to Do Before January
None of this requires dramatic action, but a few small steps are worth doing now.
- Set up or sign in to your my Social Security account by November 18 so your COLA notice reaches you online and you can see your new benefit amount early.
- Rebuild your January budget using the new figure, remembering that Medicare deductions will reduce the deposit.
- Watch for the 2027 Medicare announcement, since the Part B premium determines how much of the raise you actually keep.
- Consider where spare cash sits. If the increase leaves a little extra each month, a high-yield savings account is an easy place to build an emergency cushion while it waits.
- Be wary of benefit scams. Scams by mail, internet, phone, or in person are a standing risk, and a COLA announcement is an easy hook for them. The Social Security Administration says no government agency or reputable company will ask for upfront fees by wire transfer or gift card. Go to the official site yourself rather than clicking a link in a message.
The Bottom Line
The 2027 Social Security COLA is 3.6%, the biggest in three years, and it means roughly $75 more a month for the average retired worker starting in January. It’s a genuine increase, but it mostly keeps pace with prices rather than getting ahead of them, and Medicare premiums can claw some of it back. For anyone on a fixed income, the most useful thing to do is plan around the real deposit rather than the headline percentage, and to keep an eye on inflation, which is why a COLA exists in the first place. For a broader view of how rising rates and borrowing costs are showing up elsewhere, our look at bond yields and mortgage rates explains the other half of the story.
General information only, not personalized financial advice.

